Tuesday, 10 April 2018

Return on Investment - ROI

Assalamualaikum my dear students


Return on investment or ROI measures how much money or profit is made on an investment as a percentage of the cost of the investment. ROI shows how effectively and efficiently investment dollars are being used to generate profits. Investors use ROI to determine how successful their investment is performing, but also in comparing their ROI with the performance of other investments. 

Your ROI likely changes depending on what you are investing in and what you consider to be "favorable returns." For example, a company tracks the returns from a new marketing campaign differently than investors track returns in their investment portfolios.

However, it's safe to say that an investor cannot evaluate any investment's profitability, whether it's a stock, bond, rental property, collectible or option, without first understanding how to calculate return on investment (ROI).

The formula serves as the base from which all informed investment decisions are made, and although the calculation remains constant, there are unique variables that different types of investment bring to the equation. In this article, we'll cover the basics of ROI and some of the factors to consider when using it in your investment decisions.

How To Calculate ROI

To calculate the profit on any investment, you would first take the total return on the investment and subtract the original cost of the investment. However, ROI is a profitability ratio meaning it gives us the profit on an investment represented in percentage terms. To calculate the percentage gain on an investment, we take the profit or net gain on the investment and divide it by the original cost as shown in the formula below: 
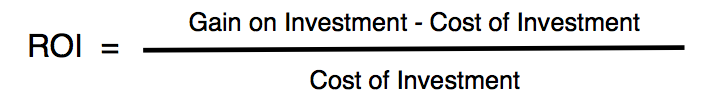

Portfolio Example Of ROI

Suppose you bought 200 shares of Bank of America Corporation (BAC) on June 5th, 2017 at the price of $22.12 for a total cost of $4,424.00. Following your purchase, bank stocks soared due to a strong economy and interest rate hikes by The Federal Reserve, ultimately boosting bank earnings. As a result, you decided to sell your shares of BAC on April 2nd, 2018 at a price of $29.31 for a total return of $5,862 and a profit of $1,438 ($5,862-4,424). 

Your ROI for BAC would be 33% ($1,438/4,424). In this case, you would have done very well for yourself.  

To take a more extreme case, the price of Apple stock was just over $5 per share in 2005, when the first iPhone was still in development. Ten years later and the price of Apple stock has skyrocketed to over $125 per share, for an amazing ROI of 2,400%, or 240% per year.
For more examples of the ROI calculation, take a look at the How To Calculate ROI Video.

Comparing ROIs With Different Initial Investments

Simply comparing the dollar value of gains between two investments doesn't provide a complete picture of the return on each investment. Since ROI is a ratio expressed as a percentage, it provides clarity as to the true gain on an investment.  

For example, Diane and Sean both told you they had made profits on their investments. Diane made $100 from investing in options while Sean made $5,000 investing in real estate. With only the total dollar value of their profits available, we might assume that Sean's investment gain was the better of the two. However, without understanding the costs of each investment, we can't make an accurate conclusion about their returns.


ROI Can Be Misrepresented

The ROI calculation remains the same for every type of investment. The danger for investors comes in how costs and returns are accounted for. Here are some investments where their returns and subsequently their ROIs can be misrepresented. 

Real Estate
Real estate can create returns in two ways, rental income and price appreciation. The investment return includes the rent collected and any price gains as the market value of the property rises. However, the costs of the investment come from many different sources including the initial purchase price, property taxes, insurance, and upkeep.

When we hear of people earning a 200% return from selling their home, they're often referring to the difference between the original purchase price and the selling price while omitting all of the costs over the years. For example, if it's an investment property, an investor might account for the rental income and price appreciation, but neglect to factor in the insurance costs, taxes and that new water heater.

Real estate can be a profitable investment, but the projected ROI on these investments can be exaggerated if all of the costs are not included. For more on real estate investing, please read How to Calculate ROI for Real Estate Investments.

Stocks
By not factoring in the transaction costs of investing in stocks, the ROI can become inflated. For example, let's say you made a $200 gain on a stock investment, but there was a $20 transaction fee charged when you bought the stock, and again when you sold it, your initial ROI of $200 would not be accurate. 

Collectibles
Collectibles like a Honus Wagner baseball card, an Action Comics #1, or the 1933 Double Eagle can sell for millions, making for astronomical ROIs when compared to their original prices. However, collectibles are rarely purchased at their original prices and, depending on the type, have high insurance and maintenance costs that reduce their ROI.

Leveraged Investments
Leveraged investments allow initial investment dollars to be multiplied many times over boosting ROI by generating sizable returns. However, the incredible ROI from the investment must be tempered by the risks taken on by investing larger sums of money. Leveraging is a double-edged sword, meaning a one dollar outlay of cash becomes two or three dollars in investment magnifying any positive returns, but the losses are equally magnified.
However, there are some leveraged investments that cap losses. For example, with plain vanilla options, the most an investor could lose is the premium or initial price paid for the option. ROI doesn't tell the whole story when it comes to leveraged investments since the risk-reward tradeoff must also be considered.  

ROI And The Length Of Time In An Investment 

ROI measures the bottom line return of any investment. However, ROI doesn't factor in the length of time an investment position is held. For example, if stock investment A has an ROI of 100% and investment B an ROI of 50%, on the surface, the 100% gain is the clear winner. But, if investment A took 10 years to achieve its 100% return while investment B took only one month to earn its 50% gain, investment A's return wouldn't be as impressive. The length of time a position is held must come into play when calculating the true return on any investment. For more on how time can impact the return on an investment, please read up on the compound annual growth rate or CAGR.

The Bottom Line


ROI can show how effectively your investment dollars are being used to generate profits. However, it's important to use ROI in conjunction with other financial ratios to give you a complete picture of an investment's potential. 

Monday, 9 April 2018

ACC 2233 - Uses of Accounting History

Assalamualaikum and hi,

We continue from our previous lecture...

Uses of Accounting History

Recreational – fact finding in the development of accounting.
Explanatory – when/why adopted and abandoned a certain practices.
Problem solving –solution of present day accounting problem.
Prediction – help predict the future.

Importance of Accounting History

  • Accounting Pedagogy – Accounting history is helpful to a better understanding and appreciation of accounting and its evolution as a social science. 
  • Accounting Policy – Accounting history can help towards a better understanding of accounting problems as well as contribute towards formulation of public policy.
  • Accounting Practice – Accounting history could provide a better assessment of the existing practices by a comparison with the methods used in the past.

ACC 2233 - History and Development of Accounting

Accounting history is defined as ‘the study of the evolution in accounting thoughts, practices and institutions in response to changes in the environment and social needs. It also considers the effect that this evolution has worked on the environment’ (Belkoui, 1983).

A brief accounting history - from 1494 to the present day

History of accounting - Pacioli
Accounting history can be traced back to a book called Summa de arithmetica, geometria, proportioni et proportionalita, written by the Italian mathematician, Luca Pacioli, in A.D. 1494.
Today, this book is regarded as an important document in accounting history: it included the first printed work on algebra and also recorded for the very first time the system of the double-entry accounting system, that became popular with Italian merchants during the Renaissance.
The book also included illustrations and diagrams drawn by Pacioli's friend, Leonardo Da Vinci.
In this book, Luca Pacioli described the use of journals and ledgers, and warned that a merchant should not rest until the debits equalled the credits! His ledger had accounts for assets, liabilities, capital, income and expenses. He also demonstrated year-end closing entries and proposed a trial balance be used to prove a balanced ledger.
Summa de arithmetica, geometria, proportioni et proportionalita was a best selling book, published across large parts of Europe, and became the basis for bookkeeping as we know it today. Even today, the double-entry accounting method is used today to record entries in both the Profit and Loss register and the Balance Sheet.

Company Legislation History

In 1844 The British Joint Stock Companies Act was an Act of Parliament that allowed companies owned by one or more individuals to be incorporated. Before this, incorporation was only possible through Royal Charter or private act. As a consequence, many businesses operated as unincorporated associations - often with thousands of members and management of these businesses, and the ability for the business to be regulated was limited. If a customer had a grievance against an unincorporated association, their only recourse was to litigate against every member individually, which was virtually impossible in many cases.
The 1844 Joint Stock Companies Act was brought in to place business and economy on a strong foundation and to increase the public's confidence in the honesty of a business.
This was followed up in 1855 by the Limited Liability Act, which limited the liability of the individual owners and directors of a business. In 1856, the Joint Stock Companies Act was updated and introduced the system still largely in use to the present day, where companies are incorporated by registration and auditors needed to be appointed for public companies to examine the balance sheet and accounts.
Today, company accounts must follow the guidelines under the Companies Act 1985. This act sets out the responsibilities of companies, their directors and company secretaries. The Companies Act only applies to companies that are incorporated under it. Sole traders, partnerships, limited liability partnerships and co-operatives are not governed by the Act.
A new Companies Act 2006 will come into place by the end of 2009. The main differences between the old and new acts are down to new provisions for company communications to shareholders, the implementation of new European Directives and clarifications on areas of common law affecting companies.

Accounting Standards history

During the 1930s and 1940s there was concern that there was no standard framework for financial accounting. This was perceived to be a bigger problem in the United States where creative accounting - making a company look more successful than it actual was - was a problem and there were a number of high profile cases where supposedly profitable companies were able to attract additional investment only to collapse a few months later with huge debts.
The American Institute of Accountants set up the Committee on Accounting Procedures (CAP) in the late 1930s as a self-regulatory body and this produced a number of Accounting Research Bulletins, which were in effect statements on accounting principles and processes. These were extremely successful in eliminating a number of questionable accounting practices. However, it did not help in establishing an underlying accounting theory for 'good' practice.
This was resolved in 1953, when the Committee on Accounting Procedures produced a standard framework of guidelines for financial accounting, called the Generally Accepted Accounting Principles (GAAP). GAAP contained the structures and rules that accountants use in recording and summarising transactions and the preparation of financial statements. Whilst GAAP was written for the United States, it was quickly adopted - with regional modifications - across Europe. GAAP continues to be maintained and updated and is still used to the present day.
In 1959, the Committee on Accounting Procedures was replaced by the Accounting Principles Board (APB). In turn, this was replaced in 1973 by the Financial Accounting Standards Board (FASB), who had additional powers to regulate the Generally Accepted Accounting Principles (GAAP). In 1990, this task was taken over by the Accounting Standards Board (ASB) and today it is the ASB who have the task of setting and monitoring accounting standards. This is the history of accounting standards.

History of Accounting - Computerised

Accounting History - UNIVAC - The worlds first commercial computer
The history of the first computerised accounting system was also implemented in 1953, when Arthur Anderson Consultancy (now known as Accenture) was asked by General Electric to implement an automated payroll processing system at their site in Louisville, Kentucky.
The system comprised of a UNIVAC 1 (UNIVersal Automatic Computer-1) computer and printer. It was the first ever commercial computer system ever implemented and became the first ever computerised accounting system.
The first computerised spreadsheet appeared in 1961 whilst the first 'off the shelf' accounting auditing system appeared seven years later in 1968.
The first ever micro-computers started appearing in the mid 1970s. At first these were expensive, cumbersome and of limited benefit to small or medium-sized businesses. Micro-computers were perceived as being an expensive hobby toy with limited benefits. Where micro-computers were used in business, it was typically used for word processing and word processing systems sold for around £10,000 per system.
Visicalc version 1.0
In 1978, two things happened in history. The Intel 8080 processor and the MOS 6502 processor became available significantly bringing down the cost of micro-computers, Apple launched the Apple II micro-computer, and the first commercially available off-the-shelf spreadsheet package was developed: Visicalc.
By modern day standards, of course, Visicalc was incredible crude, but for its time it was revolutionary: for the first time you could carry out financial modelling using a micro-computer. Visicalc revolutionised micro-computers in the business marketplace, and was a fundamental keystone in the acceptance of micro-computers for small and medium sized businesses.
By the mid-1980s, PCs became an everyday part of office life. The Apple II was superseded by the IBM PC and the IBM PC in turn was superseded by Microsoft Windows, Visicalc was superseded by Lotus 1-2-3 and then by Microsoft Excel. Accounting software packages from ACT and SAGE started to be used and by the late 1990s, PCs were used for accounting by most businesses in the UK.

Modern Day - Cloud Accounting

The most recent change in the last few years is the switch from stand alone accounting packages to cloud accounting, where employees, bookkeepers and accountants can all access the software online at the same time. This development allows people to work from home and sharing information with the relevant people.
If you want to know more about accounting history there are many accounts history books and history journals which are available which cover the history right from Luca Pacioli, to the present day.

Welcome to Semester 3, 2017/2018

Assalamualaikum and welcome to BUS1233 and ACC2233

I would like to take this opportunity to welcome you to my class for the above subjects. First of all, let me lay down some rules and what the do’s and don’ts  for the class.

Do’s

  1. Come to class.
  2. Be punctual.
  3. Mobile phones should always be in silent mode.
  4. Always bring your accounting book/manual to class.
  5. Every students’ should own a calculator (real calculator).
  6. Give full attention to the lectures.
  7. Sleep if you feel to sleep.
  8. Attempt or sit for exercises,quizzes or assignment on specified date.
  9. Submit any work given on time.

Don’ts

  1. Absent without valid reasons.
  2. Late to class.
  3. Browsing, texting and talking on the phone during lecture time.
  4. Sharing books is not recommended.
  5. Using mobile phone as calculator.
  6. Chit chatting/discussion with friends during the lecture.
  7. Sleepwalking.
  8. Absent for the exercises, quizzes or assignment without valid reasons.
  9. Late submission of exercises, quizzes or assignment.
I welcome for students who wish to bring drinks or snacks to the lecturer ….hahaha

Please regularly check the blog as I will be posting some notes, exercises, assignments etc. 

Last but not least...you are required to download an app from the google playstore. You can refer the link from my instagram. It's YIPPI and after this I will be using this as our communication platform replacing whatsapp.

Thursday, 5 April 2018

Transfer Pricing - Short Notes and Examples

Thanks to ACCA P5, I've taken this from a youtube, very good explanation and very clear. It is good for you guys to follow;

TRANSFER PRICING

Aims:
·         Profits for each division
·         Autonomy
·         Goal congruence to maximise group and divisional profits

Required for:
·         Accountability
·         Performance measurement


Transfer Price ‘Rules’

Minimum transfer price (determine by the transferor, or seller):

                   MC + lost contribution from transferring internally

Maximum transfer price (determine by the transferee, or buyer):

                   Lower of nMR and external buy-in price

Example 1: Basic

Division A produces goods and transfers them to Division B which packs and sells them to outside customers. Division A has costs of RM10 per unit, and Division B has additional costs of RM4 per unit.

Division B sells the goods to external customers at a price of RM20 per unit.


Example 2: Basic at cost plus

Division A has costs of RM15 per unit, and transfer goods to Division B which has additional costs of RM5 per unit. Division B sells externally at RM30 per unit. The company has a policy of setting transfer prices at cost plus 20%.

Calculate:
a)   The transfer price
b)   The profit made by the company overall
c)   The profit reported by each division separately


Example 3 and 4: at goal congruence

Division A has costs of RM20 per unit, and transfer goods to Division B which has additional costs of RM8 per unit. Division B sells externally at RM30 per unit.

The company has a policy of setting prices at cost plus 20%.


Example 5: limited demand and unlimited production

Division A has costs of RM15 per unit, and transfer goods to Division B which has additional costs of RM10 per unit. Division B sells externally at RM35 per unit.

Division A can sell part-finished units externally for RM20 per unit. There is limited demand externally from A, and A has unlimited production capacity.

Example 6: unlimited demand and limited production

Division A has costs of RM15 per unit, and transfer goods to Division B which has additional costs of RM10 per unit. Division B sells externally at RM35 per unit.

Division A can sell part-finished units externally for RM20 per unit. There is unlimited demand externally from A, and A has limited production capacity.


Example 7:

Division A has costs of RM8 per unit, and transfer goods to Division B which has additional costs of RM4 per unit. Division B sells externally at RM20 per unit.

Determine a sensible range for transfer price in order to achieve goal congruence, if Division B can but part-finished goods externally for:

a)   RM14 per unit.                    b)  RM18 per unit


Taken from ACCA P5 Transfer Pricing, practical approaches, goal congruence


Tuesday, 3 April 2018

Transfer Pricing

I took this from the web....
https://www.linkedin.com/pulse/transfer-pricing-meaning-examples-risks-benefits-shivangi-agarwal/

Transfer Pricing : Meaning, examples, risks and benefits

Introduction:
Transfer pricing is the setting of the price for goods and services sold between controlled (or related) legal entities within an enterprise. For example, if a subsidiary company sells goods to a parent company, the cost of those goods paid by the parent to the subsidiary is the transfer price. Legal entities considered under the control of a single corporation include branches and companies that are wholly or majority owned ultimately by the parent corporation. Certain jurisdictions consider entities to be under common control if they share family members on their boards of directors. Transfer pricing can be used as a profit allocation method to attribute a multinational corporation's net profit (or loss) before tax to countries where it does business. Transfer pricing results in the setting of prices among divisions within an enterprise.
Transfer pricing multi-nationally has tax advantages, but regulatory authorities frown upon using transfer pricing for tax avoidance. When transfer pricing occurs, companies can book profits of goods and services in a different country that may have a lower tax rate. In some cases, the transfer of goods and services from one country to another within an interrelated company transaction can allow a company to avoid tariffs on goods and services exchanged internationally. The international tax laws are regulated by the Organization for Economic Cooperation and Development (OECD), and auditing firms within each international location audit financial statements accordingly.
Arm’s Length Transaction:
Article 9 of the OECD Model Tax Convention is dedicated to the Arms Length Principle (ALP). It says that the transfer prices set between the corporate entities should be in such a way as if they were two independent entities.
A framework has been provided by the OCED in the Transfer Pricing Guidelines issued by it which provides details regarding the arm’s length price.
ALP is based on real markets and provides the MNE’s and the governments a single international standard for the contracts that allows various different government entities to collect their share of tax at the same time creating enough room for the MNE’s to avoid the double taxation.
Example:
USAco, a local company, makes small engines available to be purchased both in the United States and abroad. Outside deals are made through FORco, a wholly owned foreign company. USAco's engines cost $600 to make and $100 to market, and offer for $1,000 abroad. Notwithstanding the transfer prize utilized for deals by USAco to FORco, the consolidated income from a remote deal is $300 per engine [$1,000 final sales price -$600 manufacturing cost -$100 selling expense]. Be that as it may, transfer prices do influence the designation of that joined profit amongst USAco and FORco.
At one end, a transfer price of $600 would designate the consolidated profit of $300 totally to FORco, as takes after:
At the other extreme, a transfer price of $900 would designate the combined benefit of $300 totally to USAco, as follows.
For income tax purposes, MNCs must assign worldwide profits amid the various nations in which they function. The ideal allocation would authorize each country to tax a correct range of the taxpayer's whole profit while evading taxation of the equivalent income by more than one nation. When tax rates differ across nations, transfer pricing can have a noteworthy effect on the taxpayer's overall tax costs.
For example, the foreign tax credit restriction prevents U.S. companies operational in high-tax external jurisdictions from demanding a credit for those additional foreign taxes. These non-creditable foreign taxes upsurge the worldwide tax rate on distant earnings above the U.S. company rate of 35%. A local corporation may be able to circumvent these greater foreign taxes by changing its transfer prices to shift income out of these high-tax dominions. For example, a U.S. producer may be able to decrease a foreign marketing subsidiary share of universal profits by exercising higher prices for measured inventory sales.
Now, assume that the U.S. tax rate is 35% and the appropriate foreign tax rate is 45%. Given this rate differential, the USAco. group can decrease its worldwide taxes by using superior transfer prices for its controlled sale. For example, if a transfer price of $600 is applied for sale by USAco to FORco, the $300 gross profit is assigned entirely to FORco, and the entire tax on that profit equals the overseas tax of $135 [$300 of income X 45% external tax rate]. If a transfer price of $900 is applied for the controlled sale, the $300 gross profit is billed entirely to USAco, and the total tax on that profit parallels the U.S. tax of $105 [$300 of income x 35% U.S. tax rate].
Likewise, transfer pricing also is a pertinent issue for U.S. companies with operations in low-tax foreign jurisdictions. In these circumstances, a U.S. parent company has an incentive to move income to its low-tax foreign ancillary, for example, using lesser transfer prices on controlled inventory sales. Though shifting income to a low-tax foreign subsidiary does not everlastingly avoid the outstanding U.S tax on those low-taxed foreign earnings,what it does is defer that tax till the foreign subsidiary repatriates those profits through a dividend distribution.
A true example that shows how Google used transfer pricing to its advantage:
The regional headquarter of Google is in Singapore and it has a subsidiary in Australia. The sales and marketing support services are provided by the Australian subsidiary to users and Australian businesses and also provides research services to Google worldwide. The billing for Australian activities is done in Singapore and the payment is received from the Google entities.
In 2012-13 Google Australia earned $46 million as profit on revenues of $ 358 million. The corporate tax payment was A$7.1 million, more so, as they had claimed a tax credit of $ 4.5 million.
Ms. Maile Carnegie, the Managing Director of Google Australia was asked to respond on why Google Australia did not pay more corporate tax in Australia. She Replied by saying that the lion’s share of the taxes was paid to the country where they were headquartered. She was talking about the intellectual capital that Google owns which drives their business and it was owned outside of Australia.
Google declared that it paid US$ 3.3 billion as tax globally in 2014 on revenues of US$ 66 billion. The effective tax rate came up as 19%, while the statutory federal rate of 35% applied on Google in the US. Had Google been paying most of the tax in US, it would follow that it was not paying much taxes on the revenues that is generated from other countries.
In 2013, in Singapore US$ 4 million was paid by Google in corporate tax on undisclosed revenues from the Asia – Pacific countries as well as Australia. Compared to this, Google Australia made a payment of A$7.1 million as tax, and they did not account for most of that revenue that was booked in Singapore.
Moreover, the details of the sources of revenue that was generated from Australia was not provided by Google.
It was seen that some of the multinational companies were involved in tax minimisation using the tax incentives that were offered in accordance with the overseas jurisdiction to them which led to the evasion of tax in Australia.
MICROSOFT
The internal revenue system has investigated that Microsoft is using transfer pricing , among other things or method of booking prices and sales between subsidiaries that lends to the opportunity to report earning in lower tax jurisdiction.
Companies routinely and legally book profit overseas to avail lower tax rate and avoid hefty 35% levy on profit in the US.
Microsoft accumulated $44.8 billion non-US earning and reinvested aboard, accounting in deferred taxes of about $14.5 billion.
Microsoft did not specify how did they employ cash earned aboard but reinvestment could be anything from buying an office or parking money in the bank. While storing money overseas prevented them from repatriation tax.
Microsoft stated that "primarily due to a higher mix of earnings taxed at lower rates in foreign jurisdictions resulting from producing and distributing our products and services through our foreign regional operations centers in Ireland, Singapore and Puerto Rico, which are subject to lower income tax rates."
Forty-six percent (about $ 32 billion) of the total sales came from overseas in the year 2011 , however, pre-tax profit tripled over the past six years to $19.2 billion. In contrast, its US earning have dropped from $11.9 billion to $8.9 billion in the same period. Thereby now 68% of the total earning are made by from foreign earning.
Risks and benefits
However, some of the risks and benefits associated with transfer pricing are as follows:
Benefits:
1.    Transfer pricing helps in reducing the duty costs by shipping goods into high tariff countries at minimal transfer prices so that duty base associated with these transactions are low.
2.    Reducing income taxes in high tax countries by overpricing goods that are transferred to units in those countries where the tax rate is comparatively lower thereby giving them a higher profit margin.
Risks:
1.    There can be a disagreement among the organizational division managers as what the policies should be regarding the transfer policies.
2.    There are a lot of additional costs that are linked with the required time and manpower which is required to execute transfer pricing and help in designing the accounting system.
3.    It gets difficult to estimate the right amount of pricing policy for intangibles such as services, as transfer pricing does not work well as these departments do not provide measurable benefits.
4.    The issue of transfer pricing may give rise to dysfunctional behavior among managers of organizational units. Another matter of concern is the process of transfer pricing is highly complicated and time-consuming in large multi-nationals.
5.    Buyer and seller perform different functions from each other that undertakes different types of risks. For instance, the seller may or may not provide the warranty for the product. But the price a buyer would pay would be affected by the difference. The risks that impact prices are as follows
·      Financial & currency risk
·      Collection risk
·      Market and entrepreneurial risk
·      Product obsolescence risk
·      Credit risk


Shivangi Agarwal

Shivangi Agarwal

Business Analyst at UBS

7 articles