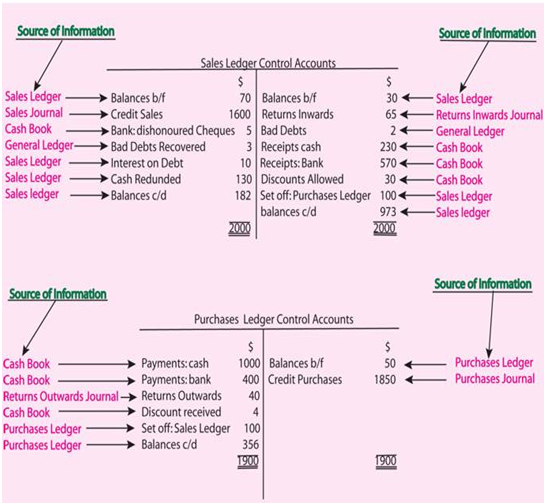
There you go! As much as I want you to succeed in my paper, I am also attaching the simple notes for the control accounts. There is also an exercise, for me it is just for an entry level. Still, you guys need to look at it. Put away your ego and learn!
Here is another exercise for control accounts. Try to attempt this question ok?
RM
Balance b/d as at 1 December 2017
- Sales ledger control account (Dr) 48,700
- Purchases ledger control account (Cr) 29,660
Transactions during the month,
Total cash sales 38,792
Total credit sales 318,990
Total cash purchases 13,212
Total credit purchases 247,340
Sales return 3,345
Purchases return 3,950
Discounts received from suppliers 3,222
Discounts granted to credit customers 3,630
Bad debts 6,750
Bad debts recovered 1,780
Cash and cheques received including from the bad debts recovered 321,780
Cash and cheques paid to suppliers 245,900
Interest charged on debtors 975
Increase in provision for bad debts 989
Transfer from Purchase Ledger to Sales Ledger 1,865
The following is a list of balances relating to Phiri Properties Ltd during 2010. The company maintains a memorandum debtors and creditors ledger in which the individual account of customers and suppliers are maintained.
These were as follows:
MK
Debit balance in debtors account 01/01/10 66,300.00
Credit balance in creditors account 01/01/10 50,600.00
Sunday credit balance on debtors ledger 724.00
Goods purchased on credit 257,919.00
Goods sold on credit 323,614.00
Cash received from debtors 299,149.00
Cash paid to suppliers 210,522.00
Discount received 2,663.00
Discount allowed 2,930.00
Cash purchases 3,627.00
Cash sales 5,922.00
Bad Debts written off 3,651.00
Interest on overdue account of customers 277.00
Returns outwards 2,926.00
Return inwards 2,805.00
Accounts settled by contra between debtors and creditors ledgers 1,106.00
Credit balances in debtors ledgers 31/12/10 815.00
Debit balances in creditors ledger 31/12/10 698.00
Required:
(a) Prepare the debtors control account as at 31/12/10.
(b) Prepare the creditors control account as at 31/12/10?
A control account is a summary account in the general ledger. The details that support the balance in the summary account are contained in a subsidiary ledger—a ledger outside of the general ledger.
The purpose of the control account is to keep the general ledger free of details, yet have the correct balance for the financial statements. For example, the Accounts Receivable account in the general ledger could be a control account. If it were a control account, the company would merely update the account with a few amounts, such as total collections for the day, total sales on account for the day, total returns and allowances for the day, etc.
The details on each customer and each transaction would not be recorded in the Accounts Receivable control account in the general ledger. Rather, these details of the accounts receivable activity will be in the Accounts Receivable Subsidiary Ledger. This works well because the employees working with the general ledger probably do not need to see the details for every sale or every collection transaction. However, the sales manager and the credit manager will need to know detailed information on individual customers, including whether a customer recently reduced their account balance. The company can provide these individuals with access to the Accounts Receivable Subsidiary Ledger and can keep the general ledger free of a tremendous amount of detail.
Sales Ledger Control Accounts And Purchases Ledger Control Accounts
Two of the most common Control Accounts are Sales Ledger Control Accounts and Purchases Ledger Control Accounts. After posting all transactions the balance of the Control Account and the sum of the detailed records in the Subsidiary Ledger should always be the same. In other words, a control account deals with summarized information while a subsidiary ledger deals with detailed information. Because the control accounts contain summarized information they are also called total accounts. Therefore a control account for a Sales Ledger can be called a Sales ledger Control accounts or Total Debtors Account. A control account for a Purchases Ledger can be called a Purchases Ledger Control account or a Total Creditors Account.
Sources of information for entries in Control Accounts
Significance of the balances on the control accounts
The closing balances on the sales ledger control accounts should be equal to the sum total of the closing balances on the individual debtor accounts in the sales ledger. It follow as well that the closing balances on the purchases ledger control accounts should be equal to the sum total of the closing balances on the individual creditor accounts in the purchases ledger. If the respective balances are not in agreement then it would suggest some form of irregularity in the records which would need investigation.